

Cost to Sell a House: Commission, Fees, Net Proceeds
Cost to sell a house explained line by line: commission, seller closing costs, concessions, prorations, prep, and holding costs plus a net sheet template.
In short
- Net is the number: sale price matters less than proceeds after payoff, fees, credits, and prorations.
- Timing drives cash: pre-listing prep is paid before closing, while most fees deduct at closing.
- Control the levers: commission terms, concessions, and listing visuals offer the biggest choices.
Most sellers pay roughly 8% to 10% of the sale price on a straightforward sale, and anywhere from about 5% to 15% once heavy prep, large concessions, or a long holding period are counted. The real question is not the list price or even the offer, it is the net proceeds that land after the settlement statement clears.
A clean estimate starts with a seller net sheet that shows every deduction and when it happens. It also separates the costs that come out of closing from the cash that leaves long before closing.
The sections below build that net sheet line by line, then run two full examples.
Cost to Sell a House: The Net Proceeds Equation
Net proceeds start as math, not a guess. Sellers can ignore ten small line items and still end up close. Sellers cannot ignore one big line item and still trust the number. A net sheet keeps the conversation anchored on what hits the pocket.
Here is the plain equation that matches how settlement statements work:
Sale price
− mortgage payoff
− agent compensation
− seller closing costs
− concessions and repair credits
− prorations
= proceeds at closing

True net after the sale
= proceeds at closing
− pre-listing prep already paid
− holding and moving costs already paid
Two terms cause most confusion. Seller closing costs are the at-closing transaction fees like title, escrow, attorney, transfer tax, recording, and HOA paperwork. Total selling costs include those fees plus pre-listing prep, concessions, and holding costs. A seller can have low closing costs and still have a high total cost of selling.
A practical net sheet also separates estimates from facts. The sale price and commission terms come from the contract and listing agreement. The payoff comes from a lender payoff statement. Transfer tax and title customs come from local rules. Prep and holding costs come from real quotes and calendar time.
When Each Cost Hits: Pre-Listing, Closing, Post-Close
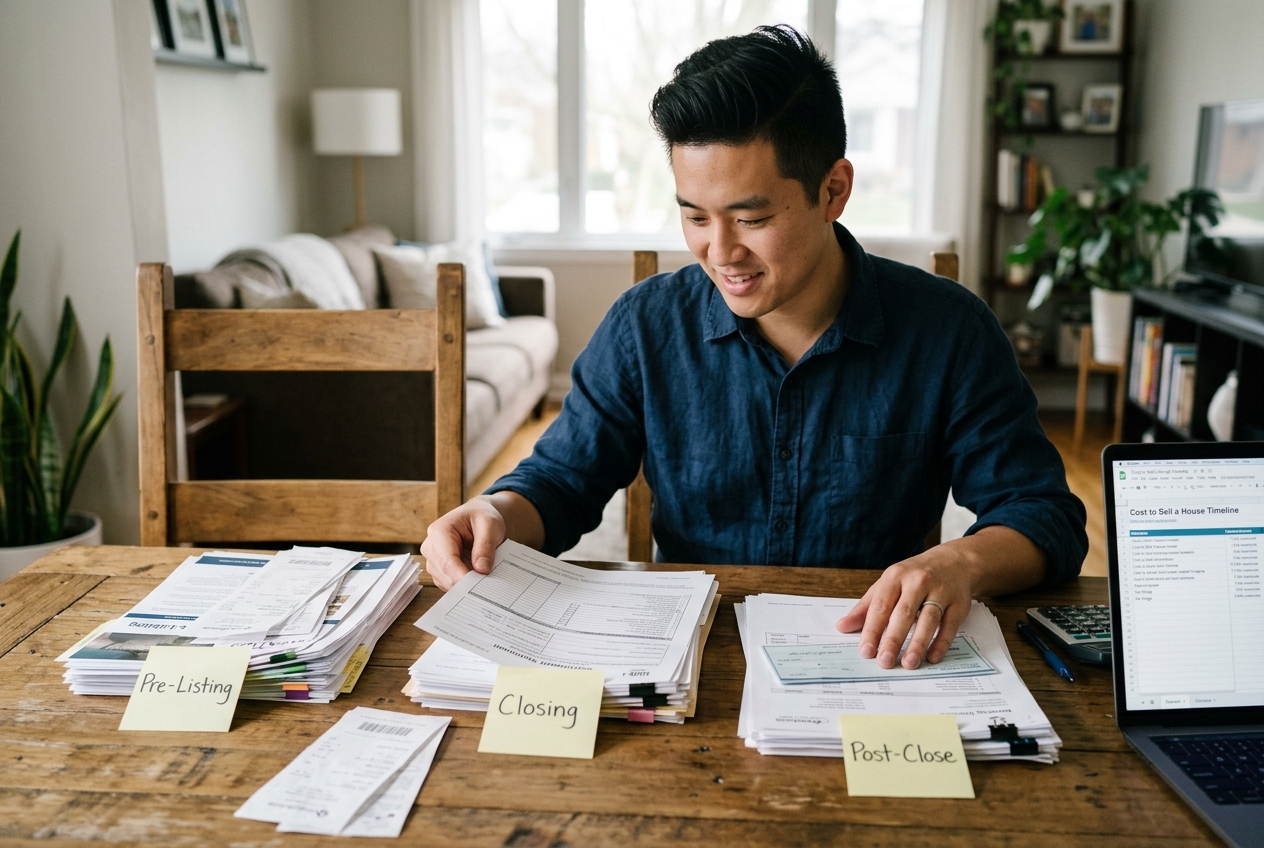
Budgeting breaks when every cost is treated like it comes out of the sale. Only the closing-phase deductions come off the top on the settlement statement. The pre-listing phase needs cash on hand, and the post-close phase can arrive before the sale proceeds feel settled.
Pre-listing costs hit first and come out of pocket. This bucket includes cleaning, yard work, paint touch-ups, pre-inspections, storage, and the listing presentation layer such as photos and staging. Low-dollar exterior work can still matter, and it is easier to control with a short scope like curb appeal upgrades that stay under budget instead of a vague wish list.
Closing costs hit second and come out of proceeds. That bucket includes the mortgage payoff, agent compensation, title and settlement fees, transfer and recording charges, prorated property taxes and HOA dues, and any seller concessions or repair credits. Lien payoffs and judgments also clear here when they appear.
Post-close costs hit last and often arrive fast. Moving trucks, overlap housing, storage, and utility overlap sit here. Even the proceeds timing can matter. Sellers should plan for sale proceeds to arrive by wire in 0 to 1 business day after closing, since some closings disburse after recording and some lenders and title companies cut off wires by time of day.
Agent Compensation and Commission Terms After 2024
Commission is negotiated, and the agreements control what gets paid. Many sellers still hear a broad 5% to 6% total as conversational shorthand, but it is not a standard rate and it is not a rule. Price point, market norms, and the service level all move the final number.
After 2024, sellers should treat listing-side compensation and any offer of buyer-agent compensation as separate conversations. The seller can only pay what the seller agrees to in writing, and each line belongs on the net sheet. The Federal Reserve has described recent shifts in how broker compensation is discussed and structured in its broker compensation analysis.
Negotiation usually lives in the terms, not only the percentage. Sellers can often discuss rate, contract term length, cancellation terms, and which marketing costs are included. Sellers comparing fee models can also review how discount and flat-fee brokerages structure their fees to translate a pitch into a line item.
A clear rule helps the agent-seller relationship. The net sheet deliverable should show the signed or assumed rates, the exact line items, and the source of each input. The pricing narrative, marketing strategy, and negotiation posture belong in the listing appointment conversation, not as hidden math inside a spreadsheet.
Mortgage Payoff and Seller Closing Costs Line by Line
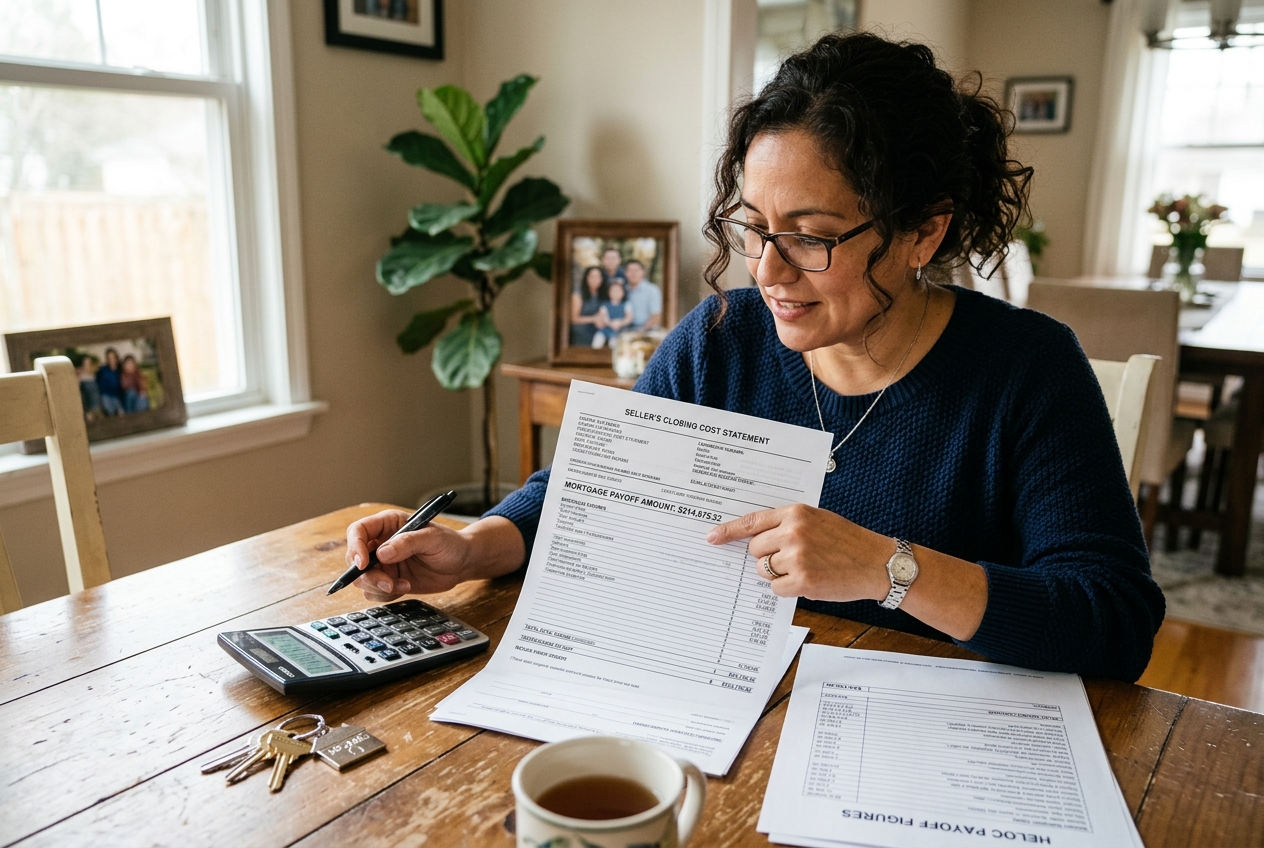
The mortgage payoff is often the biggest deduction, and it surprises sellers because it is rarely the same as the last statement balance. The payoff includes interest through the closing date, plus any lender charges tied to releasing the lien. Second mortgages, HELOCs, and solar loans can also create payoffs that stack.
A lender payoff statement solves most confusion. Sellers can request a payoff with a good-through date and confirm whether a prepayment penalty applies. A delayed closing can change the payoff through per-diem interest. Negative equity is a separate scenario that requires a lender conversation early.
Seller closing costs sit next to the payoff on the settlement statement. Each line varies by jurisdiction and contract, but the categories stay consistent:
- title services and settlement or escrow fee, which cover search, documents, and the closing process
- closing attorney fee in attorney-closing states
- owner’s title policy in markets where local custom assigns it to the seller
- transfer or excise tax and documentary stamps, which can exist at state, county, and city levels
- recording fees for the deed and releases
- HOA resale package, transfer fee, and move-out fees when an association governs the property
- wire, courier, and notary fees
- liens and judgments that must clear to deliver clean title
Local variation is real, and national averages mislead more than they help. The National Association of REALTORS tracks market-level housing and transaction context through its research and statistics resources, which can help sellers sanity-check local norms without treating any single number as universal.
A short local-verification checklist keeps the net sheet honest:
On a financed sale the buyer receives a Closing Disclosure itemising the final numbers, and the Consumer Financial Protection Bureau explains how to read each section of it. Sellers get the same level of detail on the seller settlement statement. Reading either against the net sheet before signing is the last chance to catch a line that moved.
This is general information, not legal advice. A closing attorney or title officer can confirm jurisdiction rules.
Concessions and Prorations That Reduce Net Proceeds
Concessions feel soft because the sale price on the contract stays the same. The settlement statement treats them as hard dollars. A seller concession is a credit to the buyer that reduces the seller’s proceeds at closing. Repair credits do the same thing, but they often appear after inspection.
A simple way to think about it is net equivalence. A $500,000 contract price with a $7,500 concession and a $3,000 repair credit nets like a $489,500 sale, even though the headline price did not move. That is why sellers should re-run the net sheet after inspection and again after appraisal if credits change.
Prorations cause the next surprise. Property taxes, HOA dues, and sometimes utilities get split at the closing date. The direction depends on billing. In areas that bill taxes in arrears, a seller can owe months of taxes that have not been billed yet, because the seller owned the home during that period.
Concessions and prorations also drive the most common net sheet arguments. Sellers often call them “closing costs,” but they are separate lines. Closing costs are the transaction fees. Concessions and prorations are negotiated credits and calendar math. The net sheet stays clean when it shows all three as separate deductions.
Stage your first listing in under 5 seconds
15 space types, 10 styles, MLS-compliant by default. All 11 tools on one account. Free trial credits, no credit card.
Start staging freeCosts Before the Sign Goes Up: Prep, Repairs, and Listing Visuals
Pre-listing costs come out of pocket, so sellers feel them more than line items that are deducted at closing. That reaction can lead to false savings, such as skipping basic prep that keeps the home from showing well. The goal is targeted prep that matches what buyers in that market pay for.
Most prep budgets split into two tracks. The first track is safety and function, like roof leaks, active plumbing issues, and electrical hazards. The second track is presentation, like paint, lighting, landscaping, deep cleaning, and decluttering. Cosmetic projects should tie to buyer expectations, not personal taste, and it helps to align choices with what buyers are actually looking for right now.
Listing visuals sit in the same out-of-pocket bucket, and they are one of the few selling costs a seller can cap with a choice. Physical staging often works as a rental and labor engagement quoted per room per month. Virtual staging usually prices per image. AI virtual staging is priced per image and starts around $0.24 a photo with unlimited free regenerations, which caps that line item instead of leaving it open-ended.
Clear Disclosure belongs on any digitally altered visual. Simple language works: “Disclosure: This image has been virtually staged.” and “Disclosure: This image has been digitally enhanced.” MLS Rules and broker policy can add watermark or remarks requirements, so agents should match the local standard before publishing.
Holding Costs and Alternative Selling Paths
Holding costs are the quiet budget leak, because they do not show up as a single settlement line. They show up as one more mortgage payment, one more insurance month, and one more utility cycle. A holding-cost estimate belongs on the net sheet as a monthly number and a timeline assumption.
The clean approach is to list the monthly carry lines that do not stop during escrow. Mortgage interest, property tax, insurance, HOA, utilities, and lawn or pool service often apply whether the home is occupied or vacant. Vacancy can add security, winterization, and higher utility use during showings.
Time-on-market strategy has a measurable dollar value because holding costs stack. Agents who focus on pricing, prep, and launch execution often point sellers toward tactics for shortening time on market because every extra month has a cash cost.
Selling paths change which fees show up, but they do not remove the entire fee stack. FSBO can remove the listing-side commission, yet the seller often pays directly for marketing, MLS access through a flat-fee service, photography, showings, and paperwork support. iBuyer and instant-offer models usually replace traditional listing commission with a service fee and repair deductions, and sellers can only compare them by net-to-net. Post-close costs still land either way, and a timeline plan helps, including a countdown moving checklist.
Worked Examples Plus a Copyable Seller Net Sheet Template
A worked example should show ranges, not a fake-precise total. The numbers below are assumptions for illustration only, designed to mirror a net sheet layout. Local transfer taxes, title custom, and negotiated compensation can move the outcome.
Example A uses a $325,000 starter home. Assumptions: mortgage payoff $205,000 to $215,000, agent compensation 4.5% to 6%, seller closing costs $2,500 to $6,500 based on local transfer and title custom, concessions and credits $0 to $7,500, and prorations $300 to $1,200. Pre-listing prep ranges from $1,000 to $6,000, and holding costs for a one-month listing and escrow window range from $1,800 to $2,800 depending on the monthly carry lines. Under the low-cost case, proceeds at closing come to $102,575 and true net is $99,775 after prep and holding, which puts total selling costs at $20,225, about 6.2% of the sale price. Under the high-cost case, proceeds at closing come to $75,300 and true net is $66,500, with total selling costs of $43,500, about 13.4%.
Example B uses an $850,000 move-up home. Assumptions: mortgage payoff $430,000 to $470,000, agent compensation 4% to 6%, seller closing costs $5,500 to $18,000 driven by transfer tax and attorney or escrow format, concessions and credits $0 to $25,000, and prorations $800 to $3,000. Pre-listing prep ranges from $3,500 to $18,000, and holding costs across a two-month window range from $4,500 to $7,500. Under the low-cost case, proceeds at closing come to $379,700 and true net is $371,700 after prep and holding, which puts total selling costs at $48,300, about 5.7% of the sale price. Under the high-cost case, proceeds at closing come to $283,000 and true net is $257,500, with total selling costs of $122,500, about 14.4%.
The template below is designed to copy into a spreadsheet with three columns, such as conservative, likely, and optimistic. Each row should link to a source, such as a payoff statement, a signed agreement, or a written quote.
Contract sale price
What it means: the agreed sale price before any credits
Where the number comes from: purchase agreement
Mortgage payoff
What it means: payoff(s) good-through the closing date
Where the number comes from: lender payoff statement
Agent compensation
What it means: listing-side and any buyer-side compensation the seller agreed to
Where the number comes from: listing agreement and buyer compensation addendum
Seller closing costs
What it means: title, escrow or attorney, transfer tax, recording, HOA paperwork, wire fees
Where the number comes from: title officer or closing attorney estimate
Concessions and repair credits
What it means: credits to the buyer shown on the settlement statement
Where the number comes from: inspection renegotiation and escrow updates
Prorations
What it means: tax and HOA splits through the closing date
Where the number comes from: closing disclosure or preliminary settlement statement
Proceeds at closing
What it means: sale price minus the at-closing deductions above
Where the number comes from: spreadsheet calculation
Pre-listing prep already paid
What it means: cleaning, paint, landscaping, storage, visuals
Where the number comes from: paid invoices and quotes
Holding and moving costs already paid
What it means: mortgage, utilities, insurance, movers, overlap housing
Where the number comes from: monthly bills and moving quotes
True net after the sale
What it means: proceeds at closing minus already-paid costs
Where the number comes from: spreadsheet calculation
Seller net sheet rows that match a typical settlement statement flow.
Frequently Asked Questions
How much does it cost to sell a house?
Most sellers pay roughly 8% to 10% of the sale price on a straightforward sale, and about 5% to 15% once heavy prep, large concessions, or a long holding period are counted. The range stays wide because commission is negotiated and transfer taxes and title customs vary by location. A seller net sheet keeps each line item visible so the estimate can be updated after inspection.
What are net proceeds on a home sale?
Net proceeds are what remains after the sale price covers the mortgage payoff, agent compensation, seller closing costs, concessions and repair credits, and prorations. Many sellers also track true net by subtracting pre-listing prep and holding costs already paid out of pocket. Proceeds and profit are different, since profit depends on original basis and taxes.
Is real estate commission negotiable?
Yes. Commission is set by agreement, not by regulation, so rate and terms can be discussed before signing. Since 2024, listing-side compensation and any offer of buyer-agent compensation are separate conversations that should appear in writing. The clean approach is to place the agreed terms as line items on the net sheet.
Who pays closing costs when selling a house?
Both sides pay costs, but not the same lines. Sellers often pay the payoff, agent compensation, transfer tax where it applies, recording, and prorated taxes and HOA dues, plus any concessions they agreed to. Items like the owner’s title policy and attorney fees can follow local custom and the contract, so the closing estimate should reflect local practice.
Do seller concessions reduce net proceeds?
Yes. A concession is a credit shown on the settlement statement, so it reduces the seller’s proceeds at closing even when the contract price stays the same. Repair credits function the same way after inspection. The practical step is to re-run the net sheet after inspection and again after appraisal if any credits change.
Will capital gains tax apply to a primary residence sale?
Often not, but it depends on the gain and the seller’s facts. The primary residence exclusion is commonly cited as up to $250,000 of gain for single filers and $500,000 for married filing jointly, subject to ownership and use tests. Selling costs and capital improvements can affect the gain calculation. A CPA can confirm eligibility and filing impact.